Major Paraguay Banking Crisis: Almost 3 million people, half the country locked out of their money, could the same happen in other countries?

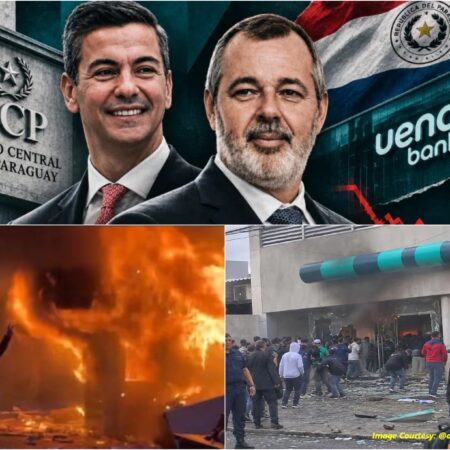
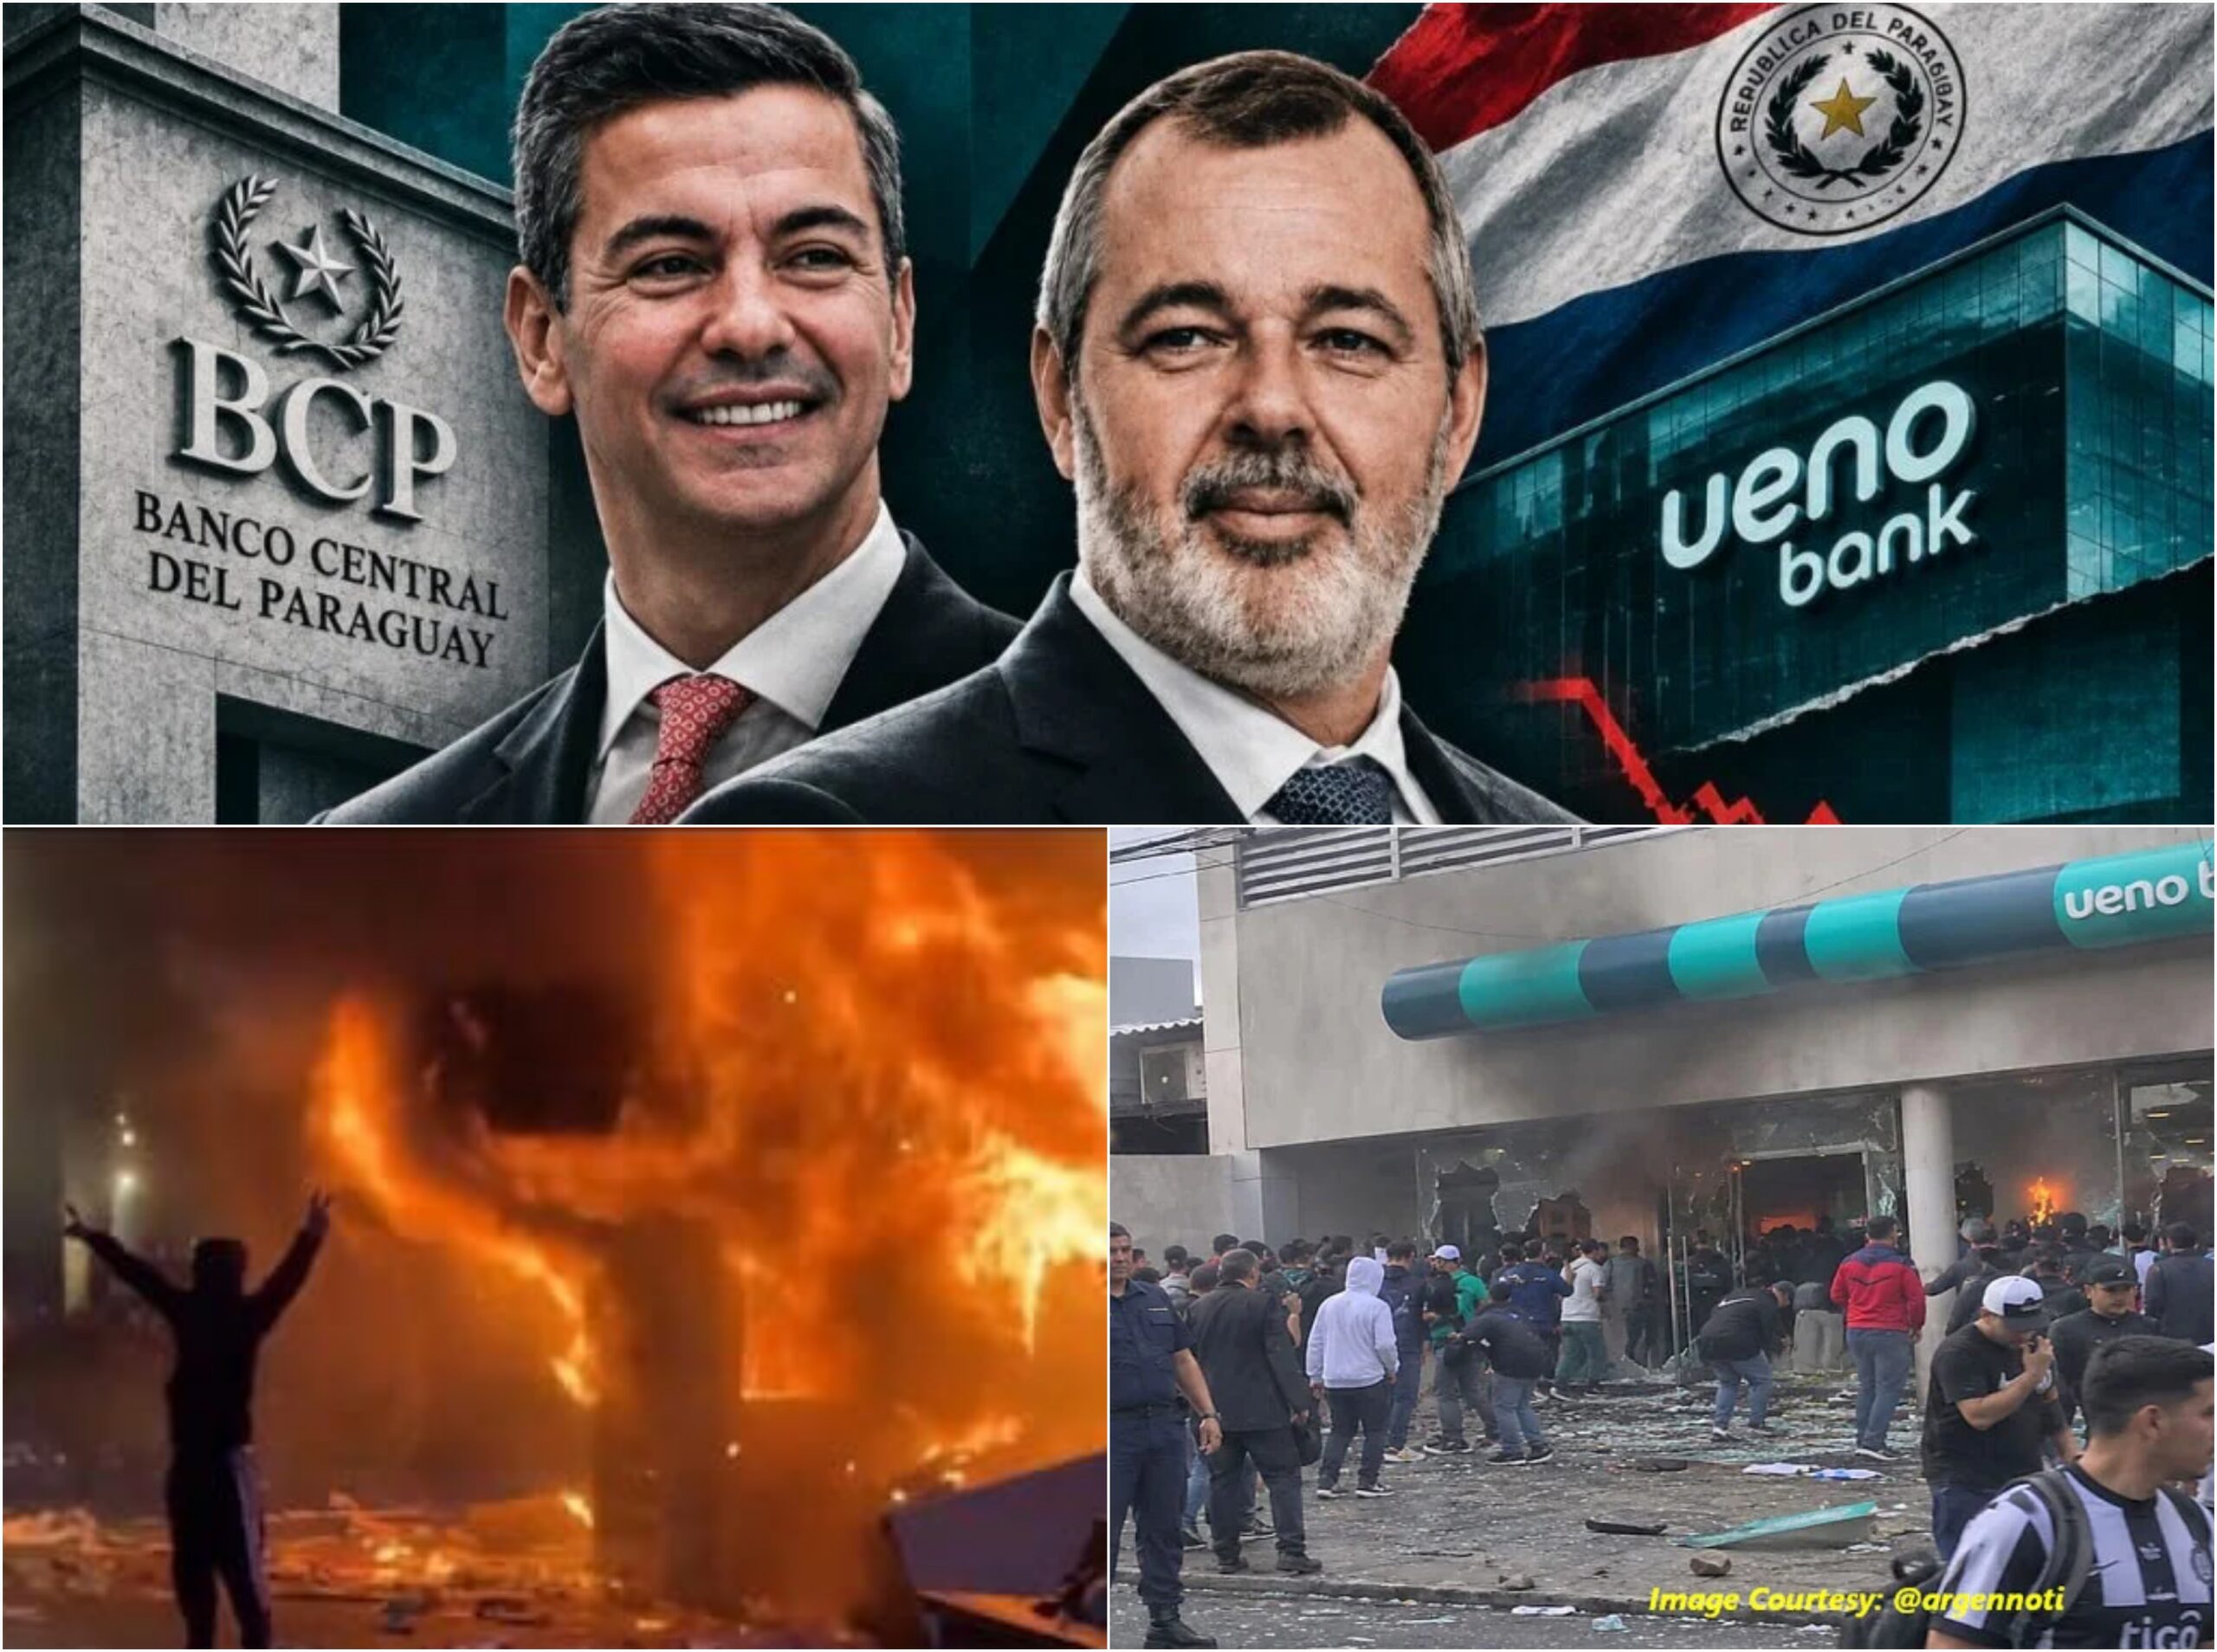
Paraguay is facing a major financial and political crisis after its Central Bank intervened in Ueno Bank, one of the country’s largest digital lenders, leaving almost 3 million customers without access to normal banking services.
The intervention has raised serious questions about financial regulation, political connections, public-sector investments and the safety of ordinary people’s savings.
But beyond Paraguay, the crisis highlights a much bigger question: could millions of people in other countries also suddenly lose access to their bank accounts?
What is happening in Paraguay right now?
On November 3, Paraguay’s Central Bank announced that it was initiating a resolution process for Ueno Bank after discovering that its solvency ratio had fallen below half the legally required minimum.
The intervention effectively suspended the bank’s normal operations. Customers faced disruptions to their access to deposits, salaries, savings and other financial services.
The consequences extend beyond ordinary account holders. Paraguay’s state social security institution, the Instituto de Previsión Social (IPS), has approximately $355 million invested in Ueno Bank. The institution also uses the bank to manage pension payments for thousands of retirees.
This has created concerns about the potential impact on pensioners and public finances. The country’s deposit guarantee system covers eligible deposits up to approximately $38,000 per depositor. Authorities have said that around 97% of depositors fall within the coverage limit.
However, compensation and access to funds are not necessarily immediate. The initial payment arrangements and recovery of larger deposits remain important challenges.
Meanwhile, prosecutors have detained bank executives as investigations into possible financial irregularities continue.
The crisis has also become a political confrontation involving President Santiago Peña, whose previous business connections to Ueno’s parent company have attracted scrutiny.
Opposition lawmakers are seeking impeachment proceedings, while the government says accountability and protecting depositors are priorities.
The Central Bank has described the failure as an institutional problem rather than evidence of a nationwide banking collapse.
Why should the rest of the world be concerned?
The Paraguay situation illustrates a risk that exists in modern banking systems everywhere. Most people believe their money is sitting safely in a bank account, available whenever they need it.
But banks do not keep every customer’s deposit in cash. They use deposits to finance loans, investments and other financial activities. This creates a mismatch between money customers may want to withdraw immediately and assets that may take months or years to recover.
When confidence disappears, even a bank with valuable assets can experience a liquidity crisis.
There are five major dangers.
1. A sudden banking panic
If customers begin withdrawing their savings simultaneously, a bank can run out of immediately available cash.
Digital banking makes this particularly dangerous because money can be transferred in seconds.
Fear can spread through social media, messaging applications and online financial communities much faster than traditional bank runs.
2. Public pension funds can be affected
Governments, pension institutions and public-sector organisations sometimes invest substantial amounts in commercial banks.
If those banks fail, public money can become trapped. The consequences may eventually affect pension payments, public services and government budgets.
3. Businesses can stop functioning
Companies depend on banking systems to pay employees, suppliers, taxes and creditors. If accounts become inaccessible, businesses can struggle to operate even if they are otherwise financially healthy.
4. Banking crises can spread across borders
Banks are connected through international lending, investment portfolios, payment systems and financial markets. A failure in one country can create losses or confidence problems elsewhere, particularly when institutions have significant cross-border exposure.
However, contagion is not automatic. It depends on the size of the failing institution, its international connections and the financial strength of other banks.
5. Governments may ultimately face the bill
When a banking crisis threatens the wider economy, governments may have to intervene. This can involve public guarantees, emergency liquidity arrangements or financial assistance.
If poorly designed, these interventions can transfer private-sector losses onto taxpayers.
Could this happen in India, the United States or Europe?
The possibility of banking failures exists in every country. However, the protections and regulatory structures differ.
India has a deposit insurance system administered by the Deposit Insurance and Credit Guarantee Corporation (DICGC).
Eligible deposits are insured up to ₹5 lakh per depositor per bank, including principal and interest. The Reserve Bank of India supervises banks and has powers to impose restrictions, take corrective action and facilitate resolution.
India’s digital payment infrastructure also creates a separate operational risk: even when banks remain financially sound, technology failures or cyberattacks can interrupt access to payments.
In the United States the Federal Deposit Insurance Corporation (FDIC) generally insures eligible deposits up to $250,000 per depositor, per insured bank, per ownership category.
The failures of Silicon Valley Bank and Signature Bank in 2023 demonstrated how quickly confidence can deteriorate when depositors move money simultaneously.
The authorities used emergency measures to protect depositors in those failures, while shareholders and certain creditors remained exposed to losses.
European countries have national deposit guarantee schemes, generally covering eligible deposits up to €100,000 per depositor per bank.
The European Union also has banking supervision and resolution arrangements designed to manage failing institutions without automatically relying on taxpayer-funded bailouts.
However, the strength and funding arrangements of individual systems still matter. The important lesson is that having deposit insurance does not mean every financial loss is automatically covered.
What are countries doing to prevent another Paraguay-style crisis?
Governments and financial regulators are strengthening several important protections. Countries are establishing or improving systems that guarantee eligible customer deposits if a bank fails.
Examples include:
– India: DICGC protection up to ₹5 lakh.
– United States: FDIC protection up to $250,000.
– European Union: generally €100,000.
– Paraguay: approximately $38,000 under its existing deposit guarantee arrangements.
The purpose is to protect ordinary savers and prevent widespread panic. Regulators are also increasing scrutiny of bank balance sheets, capital reserves, lending practices and related-party transactions.
Banks must demonstrate that they have sufficient capital to absorb financial losses. Supervisors also need to identify problems early rather than waiting until a bank becomes critically weak.
Central banks can provide emergency liquidity to eligible institutions facing temporary funding shortages. These facilities are intended to prevent temporary cash-flow problems from becoming wider financial crises.
Countries are also developing procedures to deal with failing banks without shutting down essential financial services.
These can include:
– Transferring deposits and selected assets to another bank.
– Creating temporary bridge banks.
– Restructuring liabilities.
– Replacing management.
– Making shareholders and certain creditors absorb losses before public money is used.
The Financial Stability Board has established international standards known as the Key Attributes of Effective Resolution Regimes.
Financial crises do not respect national borders. The Financial Stability Board, International Monetary Fund, Bank for International Settlements and other international institutions work with national regulators to improve financial stability.
Their work includes sharing information, monitoring financial risks and developing common standards for managing failing banks.
The new danger: digital banking and instant financial panic
One of the most important lessons from the Ueno situation is the growing relationship between digital banking and public confidence.
Traditional bank runs required customers to physically visit branches and stand in queues.
Today, customers can attempt to withdraw or transfer their money through mobile applications.
This creates a new challenge for regulators. A rumour about a bank’s financial health can spread rapidly, and thousands of customers can attempt to move their deposits almost simultaneously.
Technology makes banking more convenient, but it can also accelerate financial panic.
There is another concern: many banks now depend on common technology providers, payment networks and cloud infrastructure. A serious outage or cyberattack affecting several institutions could disrupt financial services even without a bank insolvency.
Regulators must therefore protect both financial stability and operational resilience.
The bigger question: Is the global banking system prepared?
The Ueno Bank crisis is a reminder that financial stability depends on more than the size of a country’s economy or the number of banks operating within it.
It depends on trust, transparency, effective supervision and the ability of institutions to manage failure.
Paraguay’s situation does not establish that other countries are about to experience similar crises. But it demonstrates how quickly a problem at one major financial institution can become a national political and economic issue.
The international community has spent years developing safeguards following previous banking crises. Nevertheless, recent Financial Stability Board assessments show that important weaknesses remain.
For ordinary citizens, the issue is straightforward.
People work for their money, save for retirement, pay their bills and trust banks to keep their deposits accessible. When that trust breaks down, the consequences can extend far beyond the banking industry.
The question governments everywhere should be asking is not simply whether their banks are profitable today. It is whether their financial systems can protect ordinary people when a major bank fails tomorrow.